Under KPKT's moneylender advertising rules, a licensed moneylender needs an advertising permit, and every advertisement must show the licence number and confirmation date, the permit number, the lender's name, address and phone number, and the interest rate — which cannot exceed 12% a year for secured or 18% a year for unsecured loans. Digital posts and WhatsApp content should be treated the same way.
Examples show a proposed workflow, not a guarantee that every account or plan supports it. Ask our team to confirm the channel, integration, permissions and delivery method for your setup. Staff-group notifications and group assistants require separate eligibility and integration checks; a standard one-to-one WhatsApp API account should not be assumed to access every existing staff group. Use approved individual notifications or a staff dashboard if group delivery is unavailable. Test the workflow and human handover before use.
- Regulation 8 of the Moneylenders (Control and Licensing) Regulations 2003 lists what every moneylender advertisement must show.
- You need a KPKT advertising permit before publishing; ask KPKT exactly which media and period your permit covers.
- The rate in your ad must be within the legal caps: 12% a year secured, 18% a year unsecured.
- Treat social media posts, your website, WhatsApp profile and Status updates as advertisements.
- Avoid misleading claims: approval guarantees, "no documents" promises and anything you cannot honestly deliver.
- This is general information, not legal advice. Confirm with KPKT or your lawyer before you publish.
What are the moneylender advertising rules from KPKT?
In moneylending, the advert itself is regulated — not just the loan.
Moneylending by licensed moneylenders is governed by the Moneylenders Act 1951 and the Moneylenders (Control and Licensing) Regulations 2003, administered by the Community Credit Control Division of the Ministry of Housing and Local Government (KPKT). The moneylender advertising rules KPKT enforces come mainly from Regulation 8.
According to KPKT's own FAQ, a licensed moneylender's advertisement must display:
- the licence number and the date the licence was confirmed,
- the advertising permit number,
- the moneylender's name, address and telephone number, and
- the interest rate offered.
Advertising also matters for a more basic reason. The Act's definition of a moneylender includes anyone who "advertises or announces himself or holds himself out in any way" as carrying on moneylending, as Nazmi Zaini Chambers explains. In other words, advertising loans without a licence is itself treated as carrying on the business.
We are not lawyers. This article summarises public sources. For your exact obligations and the current permit process, check with KPKT and your legal adviser.
What must every moneylender advertisement show?
Use this table as a pre-publication checklist. The examples are placeholders, not real numbers.
| Element | Example (placeholder) | Why it matters |
|---|---|---|
| Licence number + confirmation date | Licence No. XXXX/2026, confirmed DD/MM/2026 | Lets customers verify you on i-KrediKom |
| Advertising permit number | Permit No. XXXX | Shows the ad itself was permitted |
| Name of the moneylender | Sampel Kredit Sdn Bhd | Matches the licence holder |
| Business address + phone number | Office address in Johor Bahru, 07-XXX XXXX | Customers know where to go |
| Interest rate offered | e.g. "from X% p.a. (unsecured)", within legal caps | Transparent cost; must not exceed caps |
Put these details where people will actually see them: in the image or video itself, not only in a hidden caption or a link.
How do interest rate caps affect what you can advertise?
Section 17A of the Moneylenders Act 1951 caps interest at 12% a year for secured loans and 18% a year for unsecured loans, as summarised by Ying & Partners. The same source notes that compounding interest, or raising the rate when a borrower defaults, is not allowed, and that charges beyond those permitted by law are prohibited.
For your advertising, that means:
- State the rate per annum and whether it applies to secured or unsecured loans.
- Never advertise a rate above the cap — or a monthly rate that hides an annual rate above it.
- Do not advertise "no interest" or "free loan" offers that do not match the agreement.
- Make sure the advertised rate matches what your moneylending agreement will actually say.
If a customer multiplies your advertised monthly figure by 12, it should still be within the cap.
Which channels count under KPKT's moneylender advertising rules?
The regulations predate social media, so take the cautious view: if it promotes your loans to the public, treat it as an advertisement. That includes:
- Print & outdoorFlyers, banners, signboards and newspaper ads.
- DigitalWebsites, Facebook, Instagram, TikTok and search ads.
- MessagingWhatsApp Business profile, catalogue and Status updates.
Platforms add their own rules on top. Meta and Google each have financial-services advertising policies, and the WhatsApp Business Policy prohibits messaging about payday loans, paycheck advances, peer-to-peer lending and debt collection regardless of local licences. Lenders must check their own eligibility with Meta before using WhatsApp at all.
Offline, remember that banners and stickers on lamp posts or public property also break local council by-laws, permit or not.
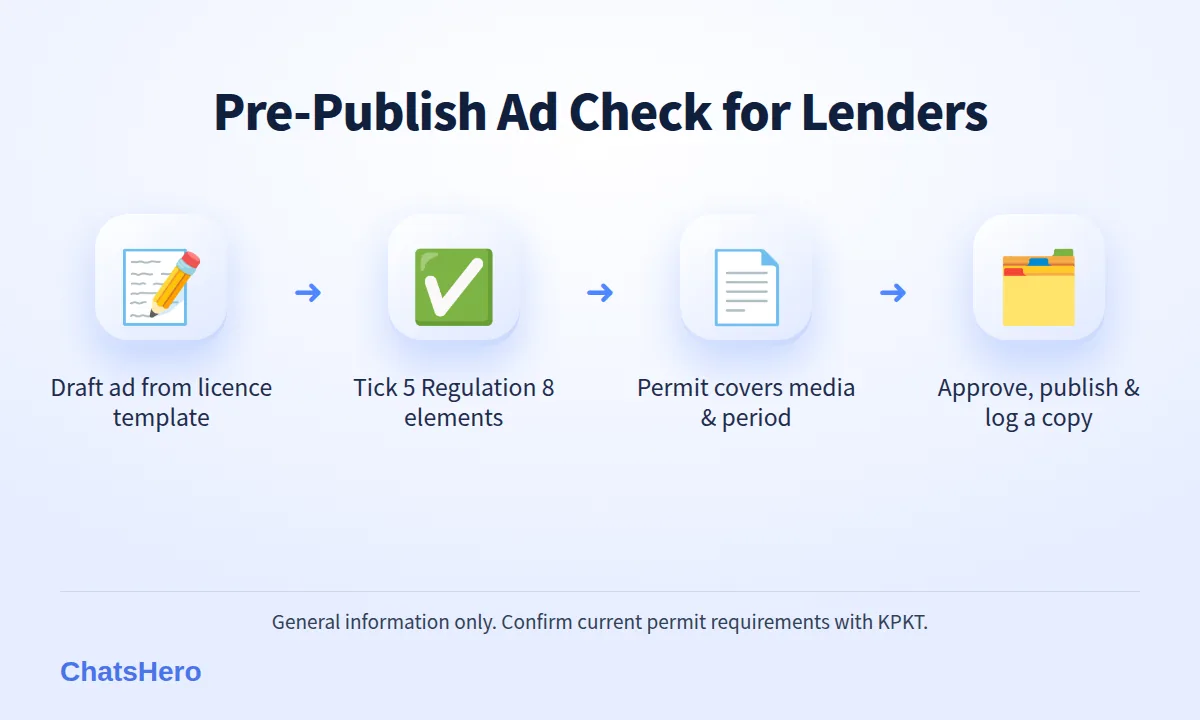
How do you check an ad before publishing it?
Draft → Check Regulation 8 → Check permit → Check claims → Approve → Log
- Draft the ad with your licence details already in the template, so nobody forgets them.
- Tick the five elements: licence number and date, permit number, name, address and phone, interest rate.
- Confirm the permit covers it. Check with KPKT which media, formats and period your advertising permit covers, and renew in time.
- Check every claim. Remove approval guarantees, "no documents" promises, unrealistic speed claims and anything else you cannot honestly deliver (see the table below).
- Check the rate against the 12% / 18% caps and against your agreement.
- Get sign-off from the person responsible for compliance.
- Log it. Record where and when each ad ran, with a copy. If KPKT ever asks, you can show it.
What claims should a licensed moneylender never make?
Some phrases look like the language of illegal lending and scams. The "Avoid" column shows wording not to use, even if your service is fast.
| Avoid | Why | Say instead |
|---|---|---|
| "Approval guaranteed" | You must assess every application | "Subject to assessment" |
| "No documents needed" | Untrue for a proper assessment | "Documents: IC, payslips, bank statements" |
| "Blacklist also can" | Encourages risky borrowing; misleading | Leave it out |
| "Pay a small fee first to release your loan" | Classic scam pattern | "We never ask for payment before disbursement" |
| "No interest" (when it is not) | Misleading about cost | The real annual rate |
Clear, boring, verifiable adverts are also easier to defend if anyone ever questions them.
How can WhatsApp support compliant moneylender advertising?
If Meta accepts your account, WhatsApp works best as the place where customers ask questions after seeing your ad, not as an ad channel. Replies should repeat the same verifiable details your advert shows and send a factual document checklist. Here is an illustrative chat for a fictional lender, Sampel Kredit Sdn Bhd in Johor Bahru:
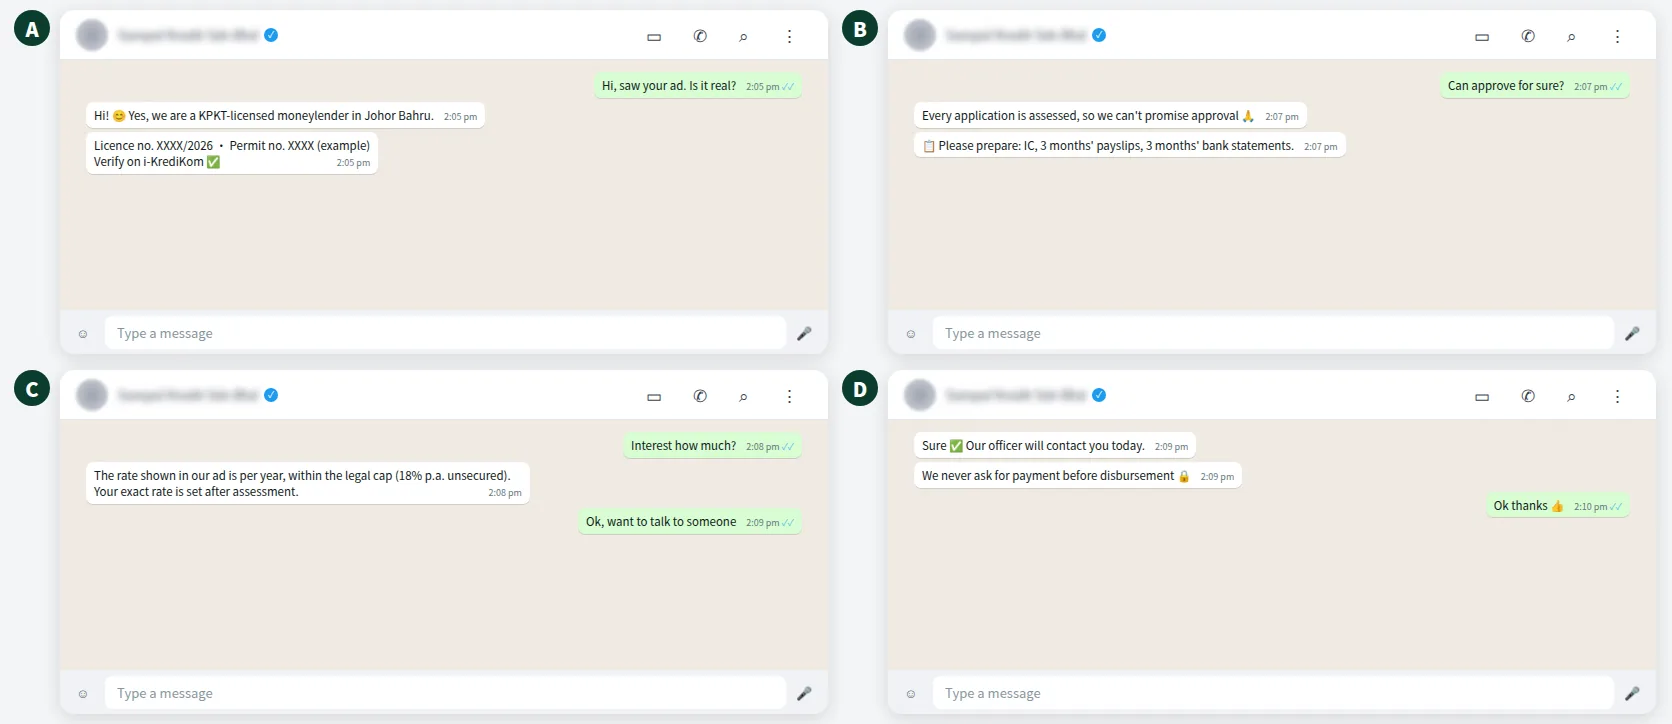
Anything about a specific amount, rate or eligibility goes to licensed staff. Never use WhatsApp for repayment chasing — Meta prohibits debt collection on the platform. ChatsHero runs on the official WhatsApp Business API and replies in English, Bahasa Melayu and Chinese; see how the AI handles mixed languages.
Want to see how this looks with your own business? WhatsApp us and chat with the ChatsHero AI.
How do you keep a record of every ad and enquiry?
A simple Google Sheet is enough for most lenders: one row per advert with channel, dates, permit number, rate shown and who approved it. With ChatsHero, the AI can ask enquirers "Where did you see us?" and record their answer in the same workbook; your team then reviews which ads bring genuine questions.
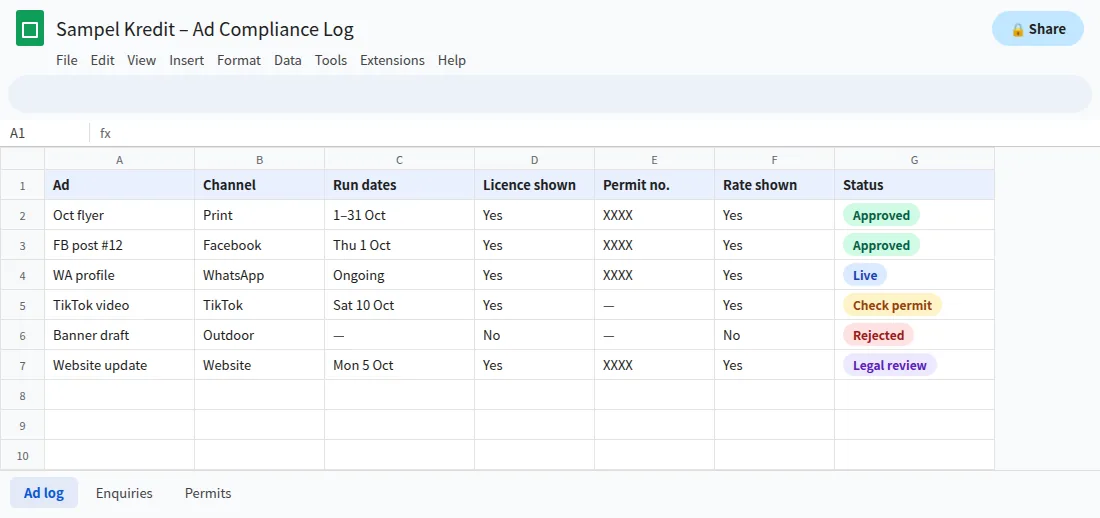
Enquiries that need a human are flagged with a "Human Agent Needed" alert in your team's WhatsApp group. Plan details are on our pricing page, and our team can walk you through the setup.
Where can customers verify a moneylender's advertisement?
Make verification easy — it is your best marketing. KPKT says customers can check a moneylender in the i-KrediKom app, on kpkt.gov.my, or by calling 03-8000 8000; complaints about licensed lenders go through KPKT's public complaints system, while unlicensed operators are reported to the police. Print "Verify us on i-KrediKom" next to your licence number on every ad, and repeat it in your first WhatsApp reply. For the WhatsApp side of the rules, see our companion guide on using WhatsApp as a licensed lender in the ChatsHero blog.
Frequently Asked Questions
What are the moneylender advertising rules from KPKT?
Under Regulation 8 of the Moneylenders (Control and Licensing) Regulations 2003, a licensed moneylender needs an advertising permit, and each advertisement must show the licence number and confirmation date, permit number, name, address, phone number and interest rate.
Do moneylenders need a permit to advertise in Malaysia?
Yes. KPKT states that advertisements must carry an advertising permit number. Ask KPKT which media, formats and period your permit covers before you publish.
What interest rate can a moneylender advertise?
The rate must be within the Moneylenders Act 1951 caps: 12% a year for secured loans and 18% a year for unsecured loans, and must match your moneylending agreement.
Does a Facebook post or WhatsApp Status count as an advertisement?
The regulations do not name specific platforms, so the safer approach is to treat any public promotion of your loans, including social media and WhatsApp content, as an advertisement that must meet Regulation 8.
Can a licensed moneylender advertise on WhatsApp?
Meta's WhatsApp Business Policy prohibits payday loans, peer-to-peer lending and debt collection and may restrict other lending, so lenders must check eligibility with Meta first. If accepted, use WhatsApp for enquiries and checklists, only with customers who opted in.
How can customers check whether a moneylender ad is genuine?
They can check the licence number in KPKT's i-KrediKom app, on kpkt.gov.my, or by calling 03-8000 8000.