A licensed money lender in Malaysia can use WhatsApp only after passing two gates: Malaysian law (a valid KPKT licence and advertising permit under the Moneylenders Act 1951) and Meta's WhatsApp Business Policy, which bans payday loans, peer-to-peer lending and debt collection and may restrict lending. If Meta accepts your account, keep WhatsApp to enquiries, licence verification, document checklists and office appointments.
Examples show a proposed workflow, not a guarantee that every account or plan supports it. Ask our team to confirm the channel, integration, permissions and delivery method for your setup. Staff-group notifications and group assistants require separate eligibility and integration checks; a standard one-to-one WhatsApp API account should not be assumed to access every existing staff group. Use approved individual notifications or a staff dashboard if group delivery is unavailable. Test the workflow and human handover before use.
WhatsApp's Business Messaging Policy says not to share or request full personal ID numbers, financial account numbers or other sensitive identifiers. Use WhatsApp for a checklist and appointment, not for full MyKad, bank-statement or payslip uploads. Collect required documents through your authorised secure portal or in person, with a privacy notice, limited access and a documented retention period. Healthcare chats should remain administrative; do not request clinical records or diagnose through the bot.
- Two separate gates apply: your KPKT licence and permits, and Meta's WhatsApp Business Policy. Passing one does not guarantee the other.
- Meta prohibits messaging about payday loans, paycheck advances, peer-to-peer lending and debt collection; check your eligibility with Meta before investing in a setup.
- Treat promotional WhatsApp content as advertising: licence number, advertising permit number, name, address, phone and interest rate.
- Interest is capped by law at 12% a year for secured loans and 18% a year for unsecured loans.
- Use WhatsApp for enquiries, licence verification, document checklists and appointments — not for cold promotions or repayment chasing.
- This is general information, not legal advice. Confirm your plans with KPKT and your lawyer.
Can a licensed money lender in Malaysia use WhatsApp at all?
For moneylenders, WhatsApp is a customer-service channel, not a sales megaphone.
Someone considering a personal loan may start with simple questions on WhatsApp: "Are you licensed?", "What documents do I need?", "Where is your office?". For a licensed moneylender, answering those questions quickly and clearly is good service — and it helps customers tell you apart from scammers.
But lending is one of the most regulated activities on WhatsApp. Before you set anything up, you need to pass two independent gates:
- Malaysian law. A valid licence from the Ministry of Housing and Local Government (KPKT) under the Moneylenders Act 1951, plus an advertising permit for any advertisement.
- Meta's rules. The WhatsApp Business Policy lists "payday loans, paycheck advances, peer-to-peer lending, debt collection, and bail bonds" among prohibited categories — regardless of any local licence.
A KPKT licence does not automatically make your business eligible on WhatsApp. Meta can decline or restrict an account in the lending category, so check your eligibility with Meta (or through your WhatsApp Business Solution Provider) before investing in a setup.
We are not lawyers. This guide summarises public sources to help you ask the right questions. For decisions about your licence, advertising or WhatsApp account, speak to KPKT, your lawyer and Meta.
What does the Moneylenders Act 1951 require from a licensed moneylender?
The Moneylenders Act 1951 and the Moneylenders (Control and Licensing) Regulations 2003 set the core rules. The points most relevant to WhatsApp are:
- Licence. Lending without a valid licence is a serious offence. The licence must be displayed at your business premises.
- Advertising permit. Under Regulation 8, as explained on KPKT's FAQ page, an advertisement must show your licence number and its confirmation date, your advertising permit number, your name, address and phone number, and the interest rate offered.
- Interest caps. Section 17A caps interest at 12% a year for secured loans and 18% a year for unsecured loans, as summarised by Ying & Partners.
- Written agreement. Loans are made under the prescribed moneylending agreement, with charges set out before the customer signs.
- Online lending needs approval. KPKT allowed selected licensed moneylenders to operate online under its guideline, with the first approvals announced in 2020 (FMT report). If you want to process applications or agreements online, check KPKT's current list of approved online moneylenders and apply first.
Customers can verify any moneylender in KPKT's i-KrediKom app or on kpkt.gov.my, so make it easy for them to do exactly that.
Is a WhatsApp message an advertisement under KPKT rules?
The regulations do not list WhatsApp by name, so take the cautious view: anything that promotes your loans — your WhatsApp Business profile description, catalogue, Status updates and any message you send first — may be treated as an advertisement. That means it should carry the Regulation 8 details and should only go out under a valid advertising permit.
Replying to a customer who asked you a question is different from promoting to someone who did not. Even then, keep replies factual: licence details, documents, office hours and how to verify you. When in doubt about whether something counts as an advertisement, ask KPKT's Community Credit Control Division before you publish it.
Also remember Meta's opt-in rule: you may only message people who gave you their number and agreed to hear from you. Bulk promotional messages to people who never asked are off the table.
What can a licensed money lender use WhatsApp for in Malaysia?
If Meta accepts your account, a narrow, service-first scope keeps the risk lower. Here is a practical split:
| Use | Suitable? | Why |
|---|---|---|
| Answering enquiries (office hours, location, process) | Yes | Customer started the chat; factual service |
| Sharing licence number and how to verify on i-KrediKom | Yes | Helps customers avoid scams |
| Sending a document checklist | Yes | Saves wasted trips; collect documents per PDPA |
| Booking an office appointment to sign the agreement | Yes | Service message the customer asked for |
| Promotions to people who did not opt in | No | Breaks Meta's opt-in rule; may breach advertising rules |
| Chasing repayments or overdue accounts | No | Debt collection is prohibited on WhatsApp by Meta |
| Promising approval or quick cash | No | Misleading; approval depends on your assessment |
Repayment matters, including any overdue account, belong with your trained staff through your usual official channels and within the law — not in an automated WhatsApp flow.
How do you set up WhatsApp for enquiries, step by step?
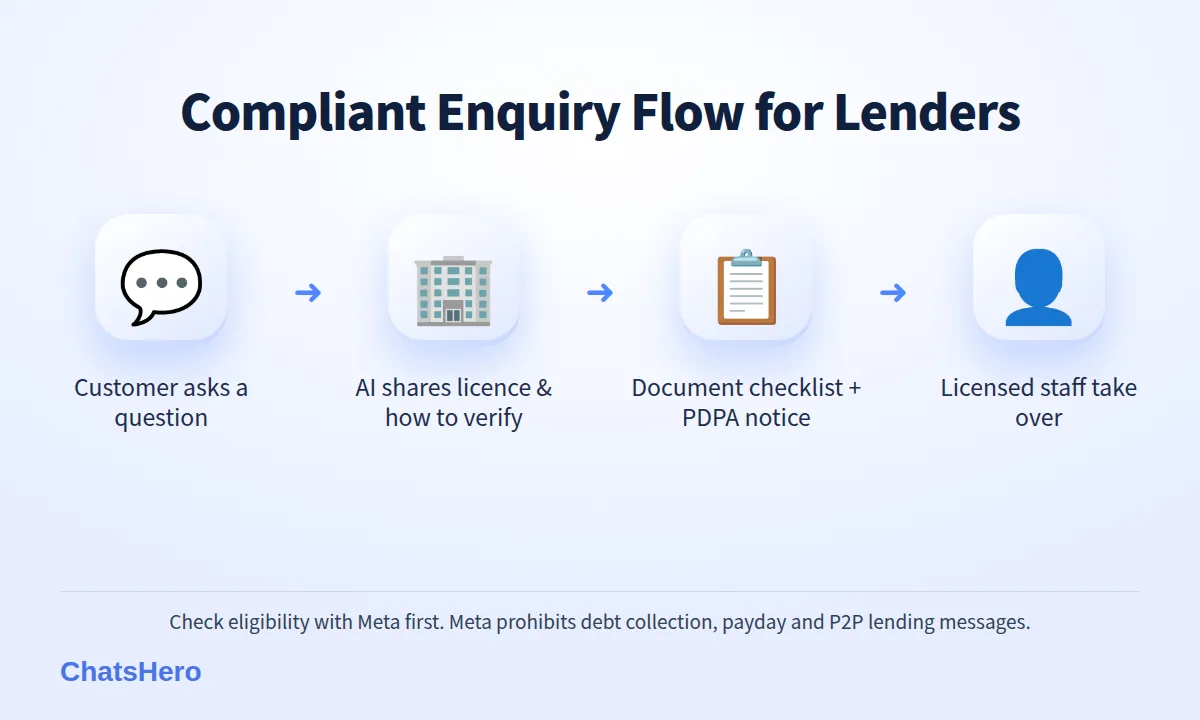
Check eligibility → Verify profile → Train FAQ → Hand over → Record
- Check Meta eligibility first. Confirm with Meta or your WhatsApp Business Solution Provider whether your lending business can use the WhatsApp Business Platform. Do not build anything until this is clear.
- Complete your business profile. Company name, office address, phone, website and — if your profile counts as an advertisement — the Regulation 8 details.
- Write factual FAQ answers. Licence details and how to verify, required documents, office hours, how the process works, and the legal interest caps. No approval promises.
- Prepare a document checklist. List exactly what you need, why, and how the documents are protected.
- Set handover rules. Any question about a specific loan amount, rate, eligibility or an existing account goes to a licensed staff member.
- Keep records. Log each enquiry and appointment so your team can follow up properly and meet your record-keeping duties.
ChatsHero runs on the official WhatsApp Business API; eligibility for your category is decided by Meta, not by us. See our plans once your account is cleared.
What should a compliant enquiry chat look like?
Below is an illustrative conversation for a fictional lender, Contoh Kredit Sdn Bhd in Kuantan. The AI answers factual questions, points the customer to i-KrediKom, sends the checklist and hands over to staff. It never promises approval or a rate.
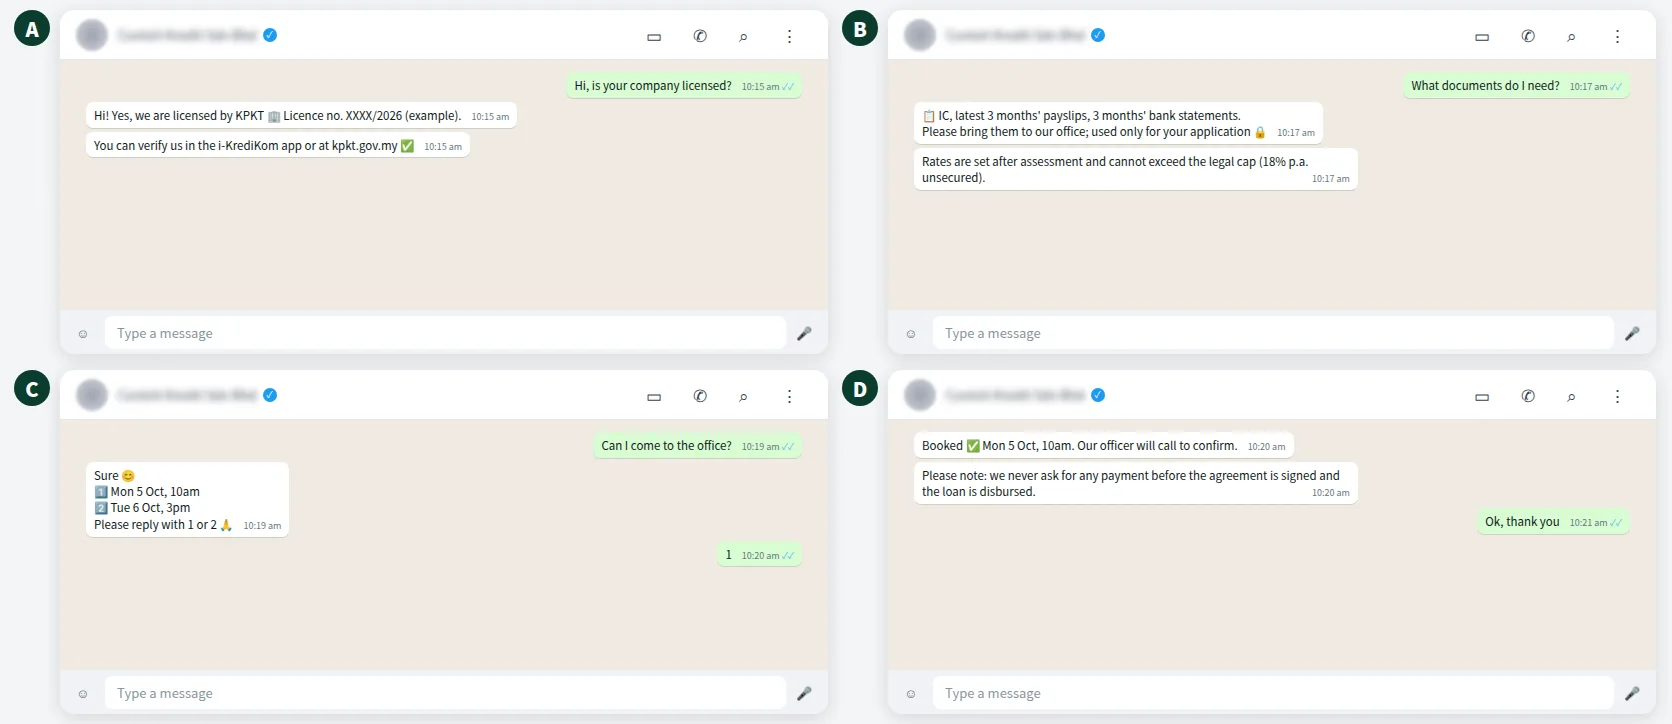
A customer in Kuantan may write entirely in Bahasa Melayu, or switch languages mid-sentence; ChatsHero replies in English, Bahasa Melayu and Chinese using the same approved facts (background: mixed-language chats).
Want to see how this looks with your own business? WhatsApp us and chat with the ChatsHero AI.
How should a KPKT licensed moneylender handle IC and payslip photos?
Loan applications involve IC copies, payslips and bank statements — prime material for identity fraud. The Personal Data Protection Act 2010, amended in 2024, applies to every copy.
- Tell customers why you need each document and who will see it before they send anything.
- Collect only what your assessment needs.
- Move documents off staff phones into a restricted folder, and mask IC numbers in any tracking sheet.
- Delete documents from abandoned or rejected enquiries on a fixed schedule, and keep what the law requires for approved loans.
- Prepare a breach plan: since 1 June 2025, a breach may need to be reported to the Commissioner within 72 hours.
- Purpose firstExplain use and retention before asking for any document.
- Least accessOnly named staff can open application files.
- Masked recordsSheets show the last 4 IC digits, never full numbers.
How can you help customers avoid scammers pretending to be you?
Scammers can copy a real moneylender's name and logo. A clear WhatsApp routine helps customers protect themselves:
- Publish your one official WhatsApp number on your website, office signboard and agreement.
- Tell every enquirer how to check your licence on i-KrediKom or kpkt.gov.my.
- State plainly that you will never ask them to transfer money before the agreement is signed at your office and the loan is disbursed.
- Remind customers they can check suspicious accounts on the police Semak Mule portal.
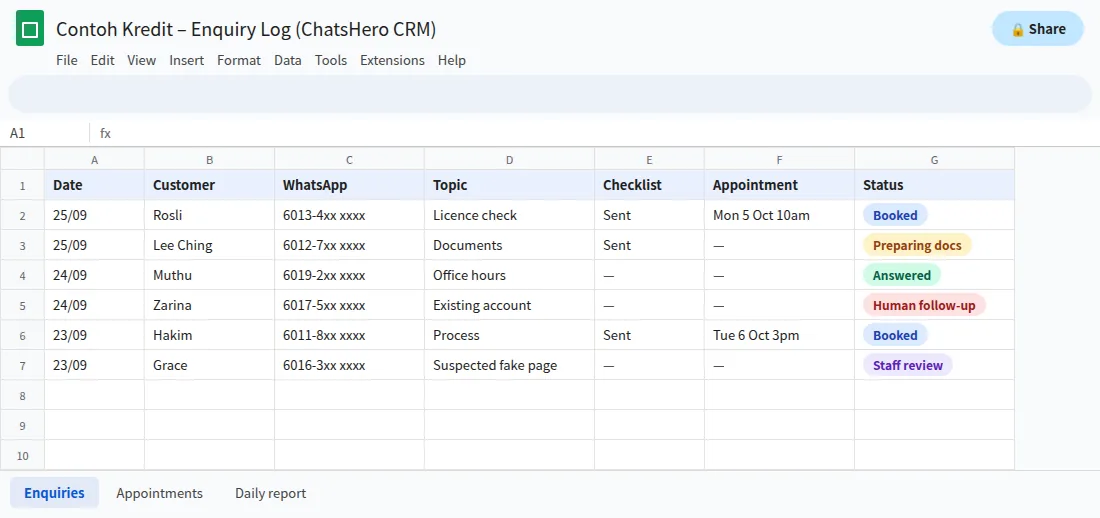
With ChatsHero, each enquiry is recorded in Google Sheets and unusual chats trigger a "Human Agent Needed" alert in your team's WhatsApp group. You can read more about who we are and how we set up compliance-first flows.
What if Meta does not approve your lending business?
Accept it and do not try to work around it with unofficial tools or personal numbers — that risks your number, your reputation and possibly your licence. Keep your phone line, office counter and website enquiry form as your main channels, and use WhatsApp only for non-lending parts of your business if Meta allows it. Compliance is what separates a licensed moneylender from everyone else in this market. If you want a second opinion on your enquiry script before you ask Meta, the companion guide on moneylender advertising rules is in our blog.
Frequently Asked Questions
Can a licensed money lender in Malaysia use WhatsApp Business?
Possibly, but only if Meta accepts the account. Meta's WhatsApp Business Policy prohibits payday loans, paycheck advances, peer-to-peer lending and debt collection, and may restrict other lending. Check eligibility with Meta first, and keep use to enquiries and document checklists.
What must a moneylender advertisement in Malaysia include?
According to KPKT, Regulation 8 requires the licence number and confirmation date, the advertising permit number, the moneylender's name, address and phone number, and the interest rate offered.
What is the maximum interest a licensed moneylender can charge?
Under the Moneylenders Act 1951, interest is capped at 12% a year for secured loans and 18% a year for unsecured loans.
Can I send repayment reminders on WhatsApp?
Meta prohibits debt collection on WhatsApp, so do not automate repayment or overdue messages there. Handle repayment matters through trained staff and your usual official channels, within the law.
How can customers check that a moneylender is licensed?
Through KPKT's i-KrediKom app, the kpkt.gov.my portal, or by calling KPKT. A licensed lender should share its licence number openly.
Can a WhatsApp chatbot approve loans?
No. A chatbot should only answer factual questions, share verification details and document checklists, and book appointments. Assessment and approval stay with your licensed staff.